

More than a decade ago, Amazon made a confident move into Brazil. They had the brand, the capital, the logistics playbook, and the same hunger for global dominance that had already turned them into the most feared company in American retail. They were going to do to Latin America what they had done to book stores, Toys R Us, and every other retailer that dared to stand in their way.
All these years later, Amazon still isn’t the #1 marketplace in Brazil.
The company that stopped them is MercadoLibre ($MELI). They still have the largest marketplace in Brazil.
Founded in 1999 in a Buenos Aires garage, MercadoLibre has built something that Amazon, for all its resources and engineering talent, has repeatedly failed to replicate: a commerce and financial ecosystem so deeply embedded into the daily economic life of an entire continent that displacing it would require rebuilding Latin America’s infrastructure itself.
This isn’t a story about a scrappy startup getting lucky. It’s a story about a management team that recognized, 27 years ago, that Latin America’s broken financial infrastructure wasn’t an obstacle. It was a moat waiting to be built.
In 2025, MercadoLibre processed $278 billion in total payment volume across 15.5 billion transactions. Their marketplace facilitated $65 billion in gross merchandise volume. Q4 revenue grew 45% year-over-year to $8.76 billion. Total full-year 2025 revenue hit $28.9 billion, up 52.4% in constant-currency and up 20x since 2018.
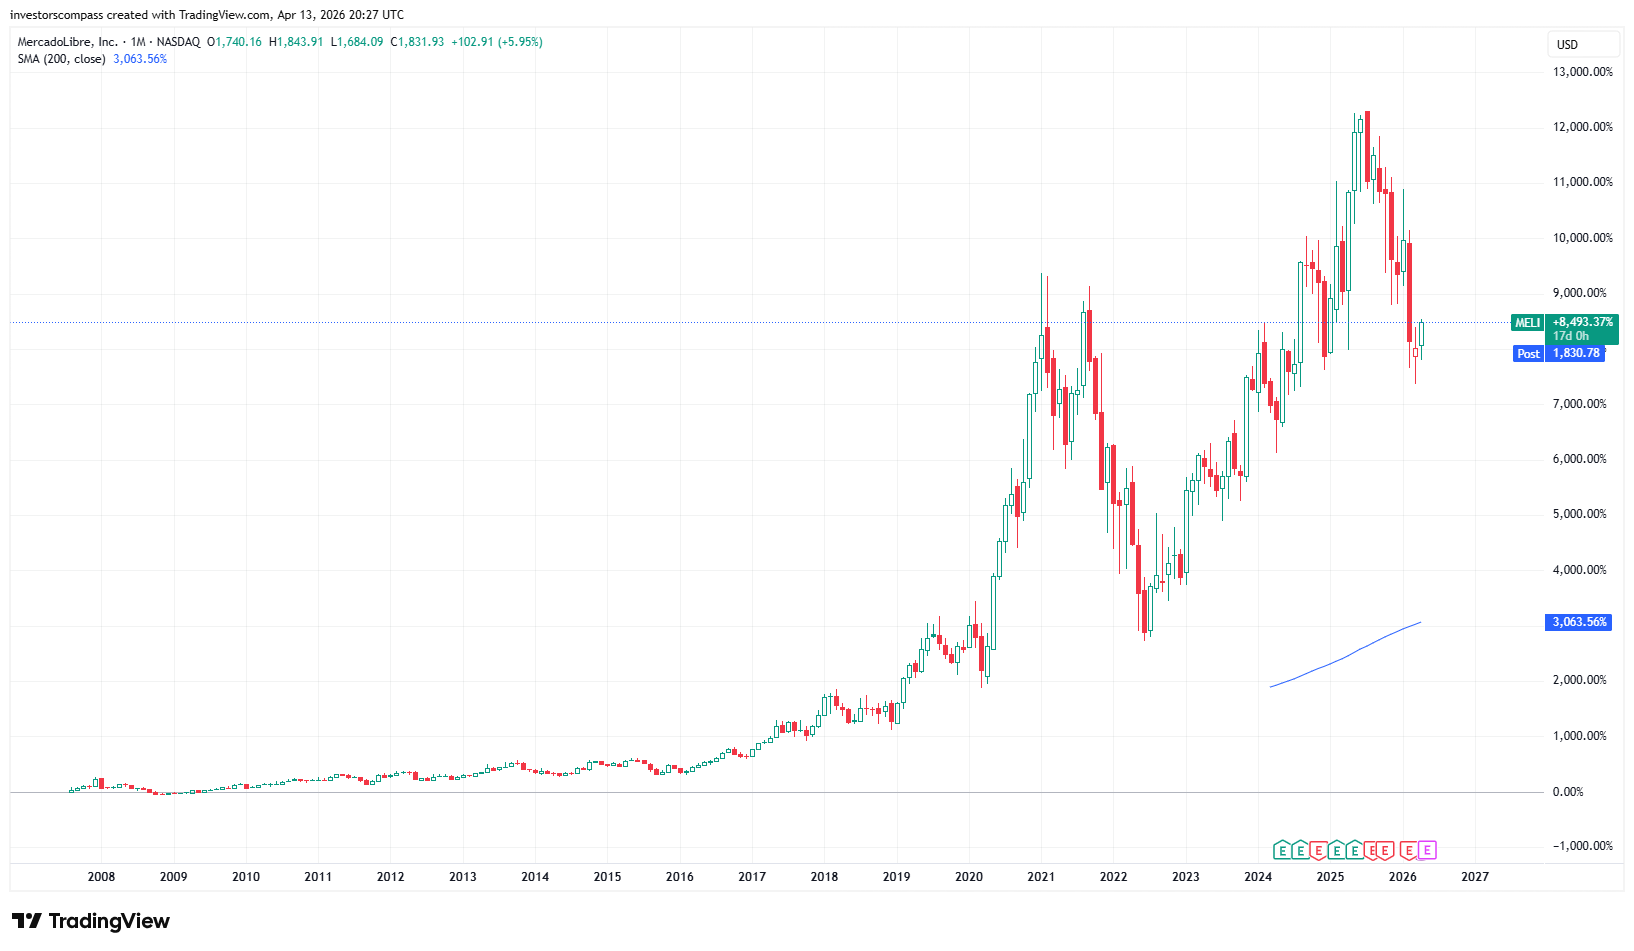
If you invested in this company when it went public in August 10, 2007, you’d be up around 8,500% now, or 86x your initial investment. They went public on my birthday. It’s a shame I was only 9 years old then. I was busy playing FIFA.
Quick note before we get into it: the Investors Compass premium tier is going up from $10/month to $20/month on May 1.
Upgrade today and lock in the current rate permanently, including Part 2 of this deep dive, every past and future deep dive, and weekly watchlists. Now let’s get back to MELI.
How MercadoLibre Was Actually Built
To understand why MercadoLibre’s competitive position is so durable, you have to understand the environment it was built in. When Marcos Galperin founded the company in a Buenos Aires garage in 1999, the original vision was simple: build an eBay clone for Latin America. Within the first few years, the management team ran straight into a structural wall that no amount of product engineering could solve.
You can’t copy-paste the American e-commerce playbook into Latin America because the two foundational pillars of modern digital commerce simply didn’t exist there.
The first problem was logistics. In the early 2000s, Latin American postal infrastructure was unreliable. Packages were routinely lost in transit, delayed by weeks, or stolen before they ever reached the doorstep. The second problem was payments. The region suffered from extremely low credit card penetration.
Tens of millions of citizens were either unbanked or had no digital mechanism to pay for goods online. Even a customer who wanted to buy something on the platform often had no way to actually complete the transaction.
In the US, Amazon could rely on FedEx, UPS, and Visa to handle all of that heavy lifting. MercadoLibre had no such luxury. So they built it themselves. To solve payments, they launched Mercado Pago. To solve logistics, they built Mercado Envios. At the time, both were purely internal solutions designed to keep the marketplace alive. Today, they’re two of the most dominant financial infrastructure businesses in Latin America.
This is the most important thing to understand about MercadoLibre’s moat. It wasn’t built in a boardroom. It was forged by necessity, in the most difficult operating environment imaginable, over 25 years of relentless iteration. That’s hard to replicate.
How MercadoLibre Makes Money
This is the part that surprises most investors when they first look at the business. MercadoLibre isn’t a simple retailer. It’s a multi-layered fee machine that’s involved in every stage of a commercial transaction. Here’s exactly where the revenue comes from.
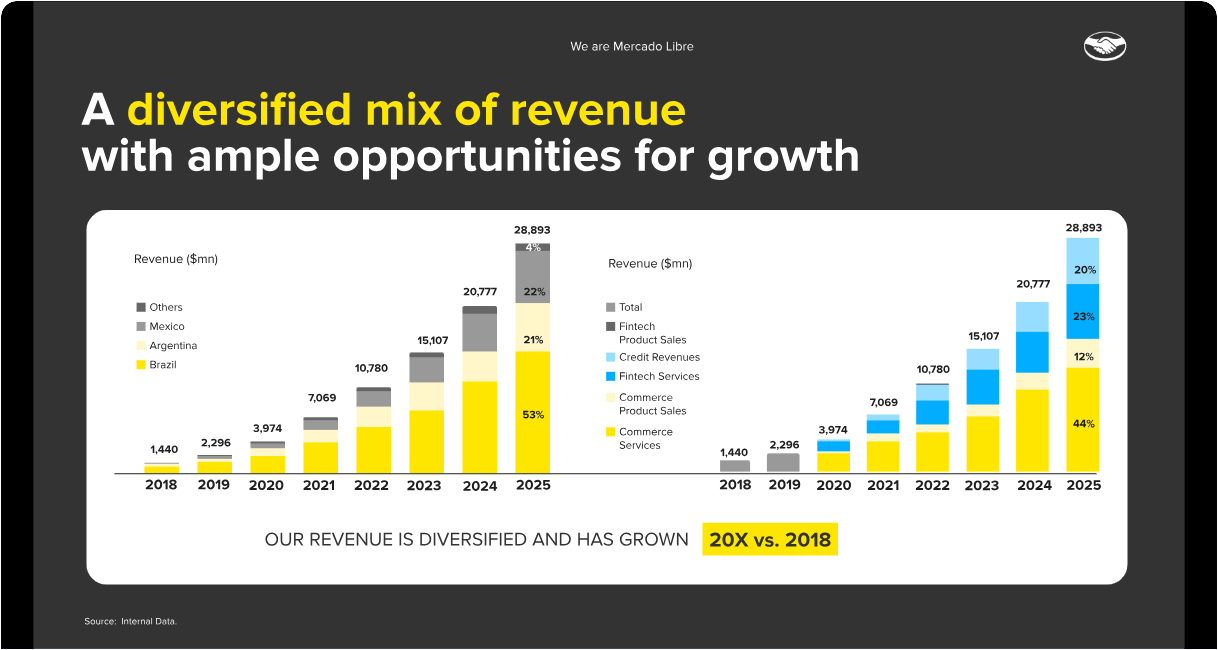
53% of its revenue came from Brazil in 2025, but you can see that the diversification has been growing, since Brazil made up most of its revenue in 2018. Argentina was another 21%, Mexico was 22% of revenues, and “Others” were 4%.
What’s interesting is the product diversification too. All of its revenue in 2018 and 2019 came from Fintech Product sales. But now, 44% comes from Commerce Services, 12% from Commerce Product Sales, 23% from Fintech Services, and 20% from Credit revenues.
MercadoLibre has replicated its commerce dominance inside the financial services industry. Here’s exactly how each stream works.
1. Commerce Services
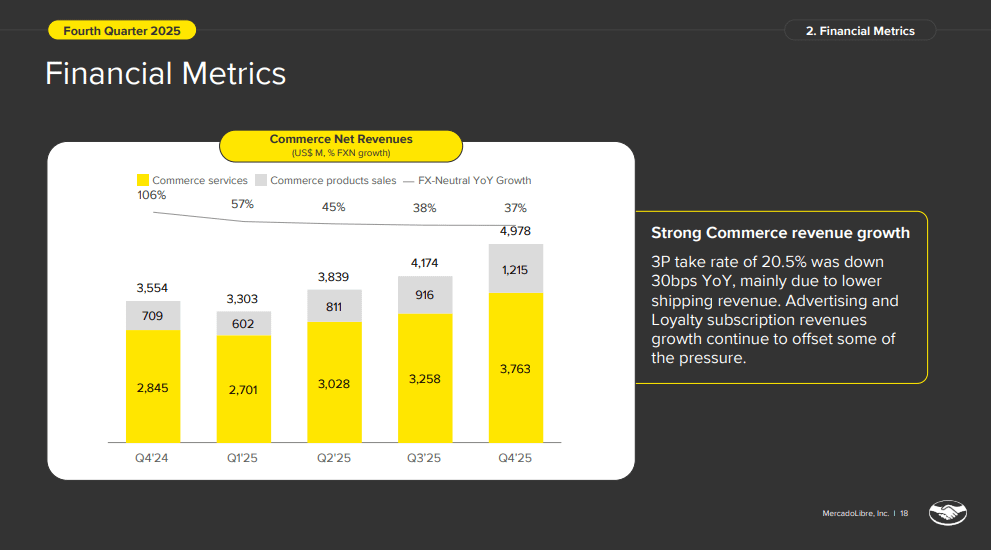
This is the largest single revenue line in the business, generating $3.763 billion in Q4 2025. It covers the final value fee MELI charges every time a seller closes a sale, flat listing fees, shipping and storage fees, advertising revenue, classified fees, and membership subscriptions. The take rate in Q4 was 20.5%. Advertising is the fastest-growing component inside this bucket, up 67% year-over-year in Q4.
2. Commerce Product Sales
MELI’s first-party (1P) inventory business. This involves the company purchasing inventory directly from manufacturers or brands and selling it to customers, as opposed to the third-party (3P) marketplace model where independent sellers list items.
This generated $1.215 billion in revenue in Q4 2025, up 71% year-over-year. This segment likely has lower margins than Commerce Services, but management said in the most recent shareholder letter, “It is also a critical lever for improving the value proposition and profitability of our Supermarket category, which remains a strategic priority”
3. Financial Services and Income (The Payments Engine)
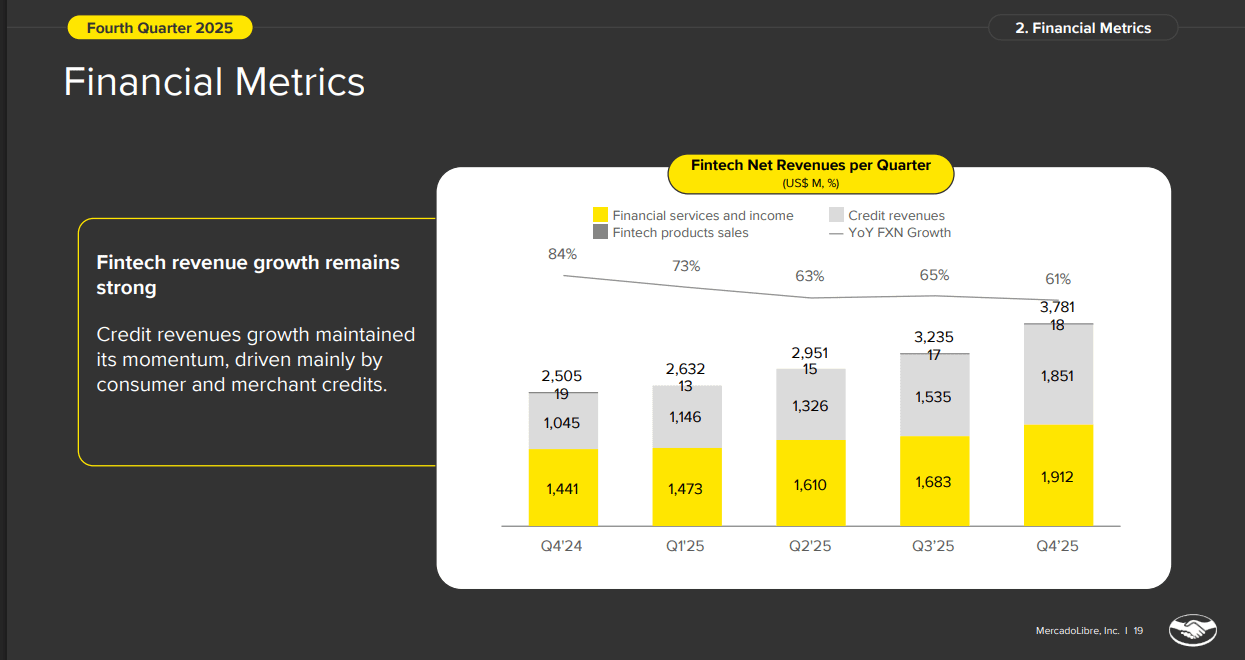
Let’s talk about Mercado Pago. MELI calls this segment Financial Services and Income, and it pulled in $1.912 billion in Q4 2025. Picture a hybrid of PayPal and a high-yield savings account. Every time someone buys a coffee with a QR code or checks out at a local shop, MELI takes a cut. The crazy part is that $55.7 billion of their payment volume in Q4 happened completely off their marketplace. They are literally taxing the offline economy. On top of that, they earn management fees on the $19 billion users currently hold in Mercado Pago investment accounts.
4. Credit Revenues ($1.851 billion in Q4 2025)
This is the lending arm. MercadoLibre just looks at its own platform to see exactly what a merchant sells and what a consumer buys. That real-time data allows them to price risk incredibly well. They issued almost 3 million new credit cards in Q4 alone, pushing their total credit portfolio to $12.5 billion.
5. Fintech Product Sales ($18 million in Q4 2025)
This is a small segment. Really small. It brought in just $18 million in Q4 2025, and it mainly refers to the card readers MercadoLibre sells to merchants so they can accept payments in person.
The easiest way to think about it is this: if a corner store or street vendor wants to take card payments, they need the device to do it. MercadoLibre sells them that device, and once that merchant is set up inside Mercado Pago, the bigger money comes later from payment processing, not from selling the hardware itself.
So, MercadoLibre isn’t just taking a cut of an online sale. It is getting paid when a merchant lists, when a buyer checks out, when a store processes a payment, when a user parks cash in Mercado Pago, and when that same user eventually takes a loan or uses a credit card. Each product makes the next one stronger, which is exactly why management keeps investing across shipping, 1P, payments, and credit even when it pressures margins in the short term.
The Addressable Market Is Still Enormous
If you look at MercadoLibre’s $28.9 billion in 2025 revenue and assume the growth story is over, you’re misunderstanding the structure of the Latin American economy.
We are talking about more than 500 million people across MercadoLibre’s markets, with a combined GDP of around $5.5 trillion. But here’s the kicker: e-commerce penetration in Latin America is still sitting at just 14%. Compare that to 27% in the US, 30% in the UK, or 32% in China. The runway here is massive. The company itself believes their sales volumes could grow to be multiple times what they are today.
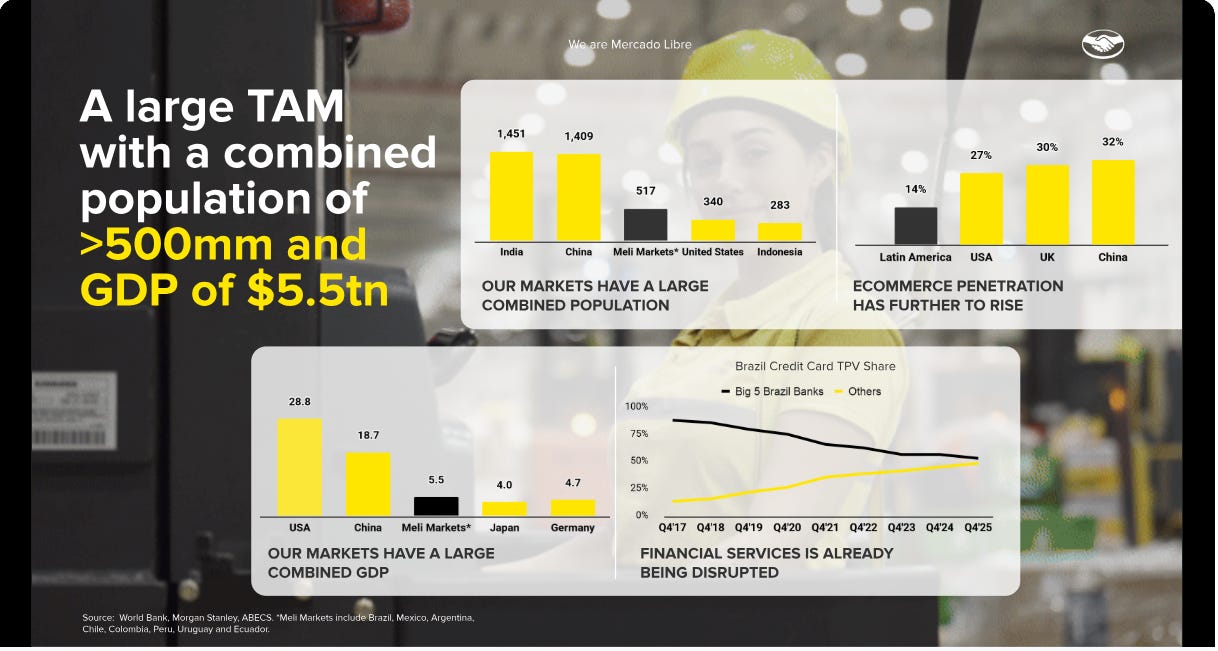
The banking side is even more wide open. A huge chunk of the region has either never had access to basic financial products, or the products they have are so bad they barely use them. In Mexico, less than 20% of people have a credit card. In Argentina, that number is just 40%.
And in Brazil, where more people do have bank accounts, the big traditional banks are so unpopular that Mercado Pago beats them on customer satisfaction by up to 30 percentage points. People aren’t unbanked because they don’t want financial products. They’re unbanked because nobody has offered them anything worth using.
That’s exactly what MercadoLibre is building. They’ve grown the money sitting in Mercado Pago accounts from $2 billion to nearly $19 billion in just three years, and they’re now the most trusted financial brand in Brazil, Mexico, Argentina, and Chile.
The Core Marketplace: 26% Compounding GMV Growth
The most visible part of what MercadoLibre does is just the marketplace itself, the place where people buy stuff. And the numbers there are genuinely impressive.
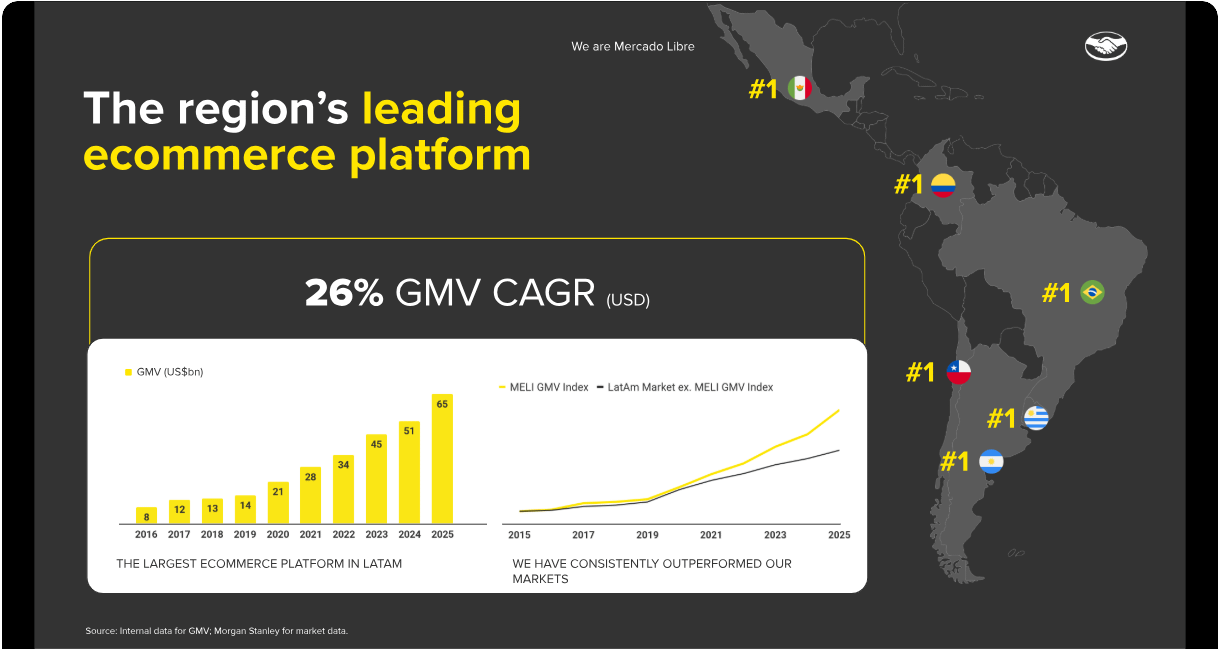
In Brazil, their biggest market, the total value of everything sold on the platform grew 35% in Q4 2025 (on a constant-currency basis). The number of individual items sold grew even faster, up 45% year-over-year. Mexico, their second largest market, matched that exact same 35% GMV growth in the quarter. Across the entire platform, full year GMV for 2025 came in at $65 billion, up roughly 26% from $51.5 billion the year before.
A big chunk of the recent acceleration came from one specific decision: lowering the free shipping threshold in Brazil. It sounds simple, but the effect is massive. New buyers who joined after the change are buying more items, shopping across more categories, and coming back more often than buyers who joined before it. Free shipping doesn’t just get people to buy once. It changes how they think about the platform entirely.
The logistics network had to absorb a huge spike in volume because of this, and it handled it while actually getting more efficient. Unit shipping costs in Brazil fell 11% year-over-year in Q4 (in local currency), and about 75% of fast shipments across the region were delivered within 48 hours. Growing fast while getting cheaper to operate is exactly what you want to see from a business at this scale.
Agentic Commerce: MercadoLibre Isn't Worried. Here's Why
There’s been a lot of noise about “agentic commerce,” the idea that AI agents will eventually shop on your behalf and cut out the marketplace entirely. MercadoLibre’s own CMO, Sean Summers, addressed this directly in their March 2026 IR Newsletter, and his take is worth paying attention to.
His argument: agentic commerce, as pitched, won’t scale. Not because the technology isn’t good enough, but because people actually enjoy shopping. They want to build conviction before they buy something. You can see this already. Amazon’s Subscribe & Save and meal kit services gave people exactly that kind of automation, and most of them quietly cancelled. The technology worked fine. People just didn’t want to hand over that decision.
What AI actually does is compress the process. Discovery, comparison, deciding what to buy, it all happens faster. But consumers still go through those stages. The steps don’t disappear, they just take less time. Amazon’s Rufus assistant was used in 40% of holiday shopping sessions and drove 66% of sales. But it wasn’t acting as an autonomous agent making decisions for people. It was just really good search.
Summers’ conclusion is the same one that Amazon, Walmart, and MercadoLibre are all betting on: agentic commerce won’t replace platforms. It will live inside them. The winners will be whoever has the deepest catalog, the richest data on their customers, and the logistics to actually deliver. That description fits MercadoLibre better than almost any other company operating in Latin America today.
The Physical Moat That Can’t Be Coded Away
You can build better software in a weekend. You can’t build a continent-wide logistics network in a decade, let alone a weekend. That’s what makes MercadoLibre’s in-house logistics arm, Mercado Envios, the hardest part of their business to compete with.
Mercado Envios is essentially their version of Amazon Logistics. It’s the network of fulfillment centers, last-mile delivery routes, and shipping infrastructure that MercadoLibre built from scratch because the existing postal systems in Latin America were too unreliable to run an e-commerce business on top of. Rather than outsourcing this to third parties, they built it themselves. And that decision, as painful and expensive as it was, is now one of their biggest advantages.
In 2025, that network absorbed a 41% jump in total shipping volume, nearly 500 million additional shipments in a single year, without the wheels falling off. And remember that unit shipping costs in Brazil actually fell 11% year-over-year. They got dramatically bigger and dramatically cheaper at the same time.
That comes from many years of building local relationships, mapping delivery routes, and figuring out where to put warehouses in markets that most Western logistics companies still find really difficult to operate in.
Amazon has spent billions trying to replicate this in Brazil and Mexico. They’ve made progress, but MELI is still ahead.
In late 2025, Amazon launched one of its most aggressive pushes in Brazil yet, waiving all FBA logistics fees for merchants during the holiday season and partnering with Nubank to give Brazilian shoppers new payment and credit options. MELI investors weren’t thrilled. The stock dipped.
But a fee waiver isn’t a logistics network. It doesn’t buy you 25 years of local relationships, mapped delivery routes, and warehouses in neighborhoods most Western companies have never heard of. The longer MELI runs this thing, the more expensive it gets for Amazon to even try to catch up.
The Fintech Crown Jewel: Mercado Pago
If the marketplace is the engine, Mercado Pago is what makes the whole thing irreplaceable.
78 million people used it actively in Q4 2025, much higher than the 35 million from three years ago. Most fintech companies either grow fast early and slow down, or they stay niche. Mercado Pago is doing neither.
What’s driving that retention is how deeply people are actually using it. This isn’t a PayPal situation where someone links it to one account and forgets it exists. People are using Mercado Pago to split bills, pay utilities, earn yield on their savings, buy groceries at physical stores by scanning a QR code, invest through Mercado Fondo, and manage their credit cards. It has become a full financial life in a single app for millions of people who never had access to anything like it before.
The Compounder Scorecard So Far
Based on my compounder checklist.
Durable moat? ✅ Three stacked on top of each other. A two-sided marketplace network effect, a physical logistics network that took decades to build, and a fintech ecosystem that 78 million people now use as their primary financial account.
Consistent growth? ✅ Q4 revenue grew 47% in constant currency (45% growth in USD). Gross merchandise value compound annual growth rate (CAGR) of 26% since 2016.
Long reinvestment runway? ✅ E-commerce penetration is still half of developed markets. Less than 20% of Mexicans have a credit card. Management itself believes GMV could be multiple times larger over the long term.
Secular tailwinds? ✅ Digital payments, financial inclusion, and e-commerce adoption across 500 million people. These aren’t short-term trends.
AI positioning? ✅ MercadoLibre’s own CMO has made the case that agentic commerce strengthens platforms with deep catalogs and first-party data. They’re building from the inside.
Coming Up In Part 2 (Paid Subs Only)
You now know how MercadoLibre was built, why the moat is real, and why the market is nowhere near tapped out. But knowing a business is great isn’t enough to make money. You need to know what you’re paying for it, what could actually break the thesis, and whether right now is a good time to buy.
In Part 2, we’ll cover:
The margin compression breakdown. MercadoLibre is intentionally taking a short-term hit to its operating margins right now. We’ll break down exactly what investments are driving this, why management is aggressively making these bets, and why this is actually a bullish signal for long-term investors rather than a red flag.
Capital efficiency and profitability trends. We’ll look at return on equity, margin trajectory across segments, and whether the current investment cycle is masking a structurally more profitable business underneath.
Its financial position. Debt, cash flow, etc.
The credit portfolio risk. With the loan book nearly doubling to $12.5 billion in 2025, we’ll assess the safety of this massive credit expansion and what it means for the bottom line.
EPS revision momentum. Are analysts revising estimates up or down? We’ll look at where consensus sits and what the revision trend tells us about how the market is thinking about this business right now.
Valuation analysis.
The bear cases. Currency risk, Argentine macro instability, and more.
The verdict. My rating on the stock and whether this is a buy right now or a wait-and-watch situation.
Part 2 drops on Wednesday for paid subscribers.
The premium tier is going up from $10/month to $20/month on May 1. Upgrade today and you’ll lock in the current rate permanently, getting Part 2, every future deep dive, and the full watchlist at the price it is right now.
UPDATE: Here’s Part 2!
MercadoLibre Deep Dive: Falling Margins Look Awful. That’s the Opportunity (Part 2/2)

Welcome back to the MercadoLibre deep dive. PART 2. It’s nice to have you here.
Good stuff! We are long MELI here! The big question is whether this margin squeeze is just a temporary phase of heavy investment or a permanent scar from Amazon’s push into Brazil.